Qatar — An Energy Giant with a Fatal Vulnerability: 96% LNG Export Loss, Tokenization Without Bitcoin, and a Crypto Ban | SforNews
QATAR — AN ENERGY GIANT WITH A FATAL VULNERABILITY
The Diagnosis of the Old Model and Its Place in the New Energy-Digital System
INTRODUCTION: A BRIEF DIAGNOSIS
Qatar is the most contradictory point on the map of the emerging energy-digital system.
It is simultaneously:
• An Energy Giant With Lost Export Channels
Before the conflict, Qatar accounted for roughly one-fifth of global LNG exports — around 20 million tons per quarter.
After the closure of the Strait of Hormuz, exports fell to less than 2 million tons [1][2].
• An Institutional Investor
The Qatar Investment Authority (QIA) manages approximately $500 billion in assets.
In 2026, QIA expanded its fund-of-funds program from $1 billion to $3 billion, adding five new funds, including Liberty City Ventures — focused on blockchain technologies, with approximately $2.4 billion under management [3][4].
• A Builder of Digital Infrastructure
The Qatar Central Bank (QCB) has completed development of the infrastructure for a digital riyal (CBDC).
The QFC Digital Assets Framework, introduced in September 2024, legalizes the tokenization of real estate, sukuk, equities, and ETFs.
Dukhan Bank became the first Qatari Islamic banking institution to connect to J.P. Morgan Kinexys — a blockchain-based deposit network enabling instant cross-border settlements 24/7 [5][6][7].
• A Country With a Strict Cryptocurrency Ban
The QFC Regulatory Authority explicitly states:
“Virtual Asset Services cannot be conducted in or from the QFC.”
The ban covers digital substitutes for currency used for payments or investment [5][8][9].
Qatar’s Paradox
A country that is systematically building a new financial infrastructure — CBDC, tokenization, blockchain-based settlements — categorically excludes Bitcoin from that architecture.
It recognizes blockchain but rejects cryptocurrencies.
It creates a digital riyal but does not create an energy derivative.
It invests in tokenization but not in the monetization of energy.
Qatar is making the same mistake as Russia — building a new system on old principles.
But if Russia can change course, Qatar may not have that luxury.
Its energy is locked inside the Persian Gulf.
Its financial system is being built around tokenized assets that cannot be physically exported.
SECTION 1. THE OLD MODEL: WHAT EXISTED AND WHAT BROKE
Qatar’s economic model over the past several decades rested on three pillars:
LNG Exports
The foundation of government revenues and foreign-currency inflows.
Qatar was the world’s largest LNG exporter [1][2].
Dollar Peg
The Qatari riyal is pegged to the U.S. dollar and operates within the broader petrodollar system [1].
State Control
Centralized economic management through QIA, QatarEnergy, and government ministries [1].
This Model Has Broken
Loss of 96% of LNG Exports in a Single Quarter
Before the conflict, Qatar exported approximately 20 million tons of LNG per quarter.
After the closure of the Strait of Hormuz, exports fell below 2 million tons.
Unlike Saudi Arabia and the UAE, Qatar has no alternative export routes — its tankers physically cannot reach Asian buyers [1][2].
A $5.8 Billion Budget Deficit in One Quarter
The largest quarterly deficit since 2016.
The North Field East project, which was supposed to increase capacity by 85%, has faced delays.
The strike on Ras Laffan in March 2026 forced QatarEnergy to shut down its main export facility for the first time in nearly 30 years [1][2].
Economy Under Pressure
Qatar’s GDP is projected to contract by 6.1% in 2026, compared with an expected 6.1% growth rate before the conflict.
A country that had spent decades serving as a symbol of energy superpower status found itself trapped inside its own model [1].
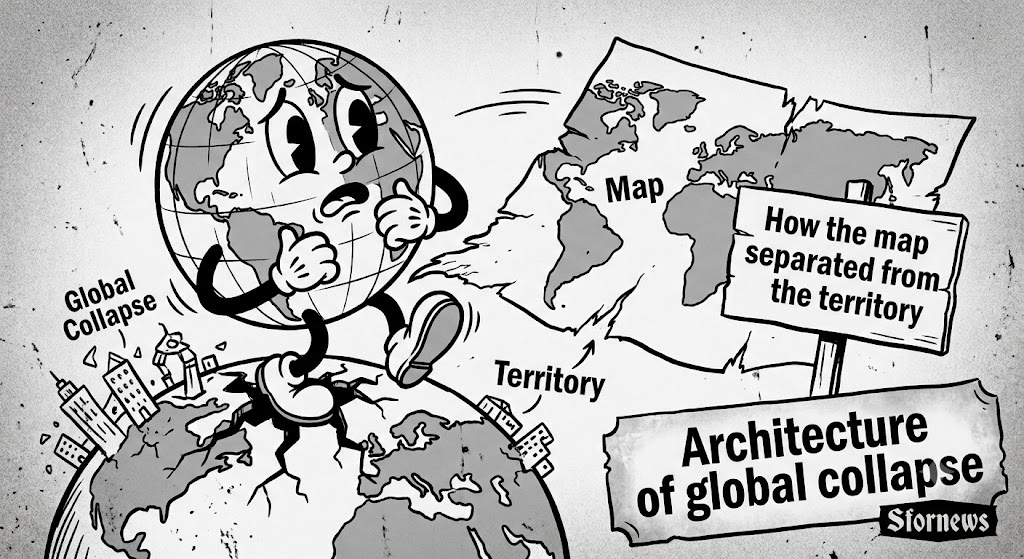
The map — oil revenues, the dollar peg, and state control — stopped reflecting the territory:
Lost exports.
Budget deficit.
Energy blockade. [1][2]
SECTION 2. ENERGY PROFILE: WHAT QATAR HAS — AND WHAT IT DOESN’T
Qatar is an energy giant, but its model depends heavily on exports.
| What Qatar Has | What Qatar Lacks |
|---|---|
| World’s third-largest natural gas reserves | Alternative export routes |
| World’s largest LNG exporter before the conflict | A flexible economy independent of gas |
| Developed LNG infrastructure at Ras Laffan | Sufficient channels for energy monetization |
| Strategic location in the Middle East | Full independence from the Strait of Hormuz |
The Key Fact
Qatar is not an energy-deficient country.
It has energy.
Its main challenge is monetizing that energy when physical export channels are blocked.
The North Field East project, which was supposed to increase capacity by 85%, has faced delays [1][2].
A New Element: Digital Infrastructure Without an Energy Derivative
QCB has completed the infrastructure for the digital riyal (CBDC).
The first stage focuses on large interbank payments using DLT and AI.
The official launch is not expected before 2027 [5][6][7].
The QFC Digital Assets Framework, introduced in September 2024, legalizes tokenization of:
- real estate;
- sukuk;
- equities;
- ETFs.
But cryptocurrencies are explicitly excluded and classified as “Excluded Tokens” [5][6][7].
The Result
Qatar is building institutional digital infrastructure.
But it is infrastructure without an energy derivative.
CBDC — digital fiat.
Tokenization — digital securities.
Blockchain settlements — digital SWIFT.
None of these instruments monetizes energy.
Qatar is creating a new wrapper for an old system.
SECTION 3. QATAR’S POSITION ON MINING AND CRYPTOCURRENCIES
This is where Qatar’s main paradox emerges.
Current Situation
Crypto mining in Qatar is practically nonexistent.
Its share of global hash rate is minimal.
Cryptocurrencies are prohibited.
Regulatory Environment
QCB Circular 6/2018
Prohibits cryptocurrency trading and their use as a means of payment [5][8][9].
QFCRA Alert 2019
Confirmed the prohibition of virtual assets within the QFC [5][8][9].
QFC Digital Assets Framework — September 2024
Legalizes tokenization of real-world assets — including real estate, sukuk, equities, and ETFs — while explicitly excluding cryptocurrencies [5][6][7].
Virtual Assets Law — 2025
Adopted in 2025 and entered into force in January 2026.
It creates a regulatory framework for tokenization, but not for cryptocurrencies [5].
QIA: $500 BILLION THAT IS NOT GOING INTO BITCOIN
The Qatar Investment Authority manages approximately $500 billion in assets.
In 2026, QIA expanded its fund-of-funds program from $1 billion to $3 billion, adding five new funds, including Liberty City Ventures, focused on blockchain technologies and managing approximately $2.4 billion [3][4].
QIA CEO Mansoor Al-Mahmoud stated clearly:
“We explore opportunities in blockchain. It is a space that interests us — not the currency itself.” [3][4]
Rumors that QIA could invest $500 billion in Bitcoin were officially denied [3][4].
Qatar’s Paradox
Qatar invests in the technology, but not the asset.
It is a strategy of:
“Blockchain Without Bitcoin.”
That strategy may work in a stable system.
But it becomes problematic when energy cannot be physically exported.
Blockchain without Bitcoin is like the internet without data.
SECTION 4. THE POSITION OF QCB AND THE REGULATORS
Qatar operates a two-level regulatory model [5][6][7].
4.1. QCB — Qatar Central Bank
Mandate
- Payment systems;
- AML/CFT;
- operational resilience;
- monetary policy [5].
CBDC
The infrastructure for the digital riyal has been completed.
The first stage focuses on large interbank payments using DLT and AI.
Official launch: not before 2027 [5][6][7].
Cryptocurrency Regulation
Trading and use of cryptocurrencies as a means of payment are prohibited under Circular 6/2018 [5][8][9].
4.2. QFCRA — QFC Regulatory Authority
Mandate
Regulation of financial services within the QFC, licensing, and supervision [5].
Position on Cryptocurrencies
“Virtual Asset Services cannot be conducted in or from the QFC.”
The prohibition includes digital substitutes for currency used for payments or investment [5][8][9].
Exception
Tokenization of real-world assets — including real estate, sukuk, equities, and ETFs — is permitted under the QFC Digital Assets Framework of September 2024 [5][6][7].
4.3. Infrastructure Oversight — CRA + NCSA
Cybersecurity
The NCSA — National Cyber Security Agency oversees hosting, nodes, cloud environments, and key management [5].
Blockchain Blueprint
The CRA — Communications Regulatory Authority developed a national blockchain implementation plan together with Hamad Bin Khalifa University and Qatar University [5].
The Key Principle
Licensing, supervision, and auditability are embedded into the architecture from day one.
“Compliance is not the second stage. It is the entry ticket.” [5]
The QCB Paradox
It is creating a digital riyal for banks, but not for citizens.
It prohibits cryptocurrencies while building infrastructure for tokenization.
It invests in blockchain technologies but not Bitcoin.
This is not a strategy.
It is caution.
SECTION 5. ARCHITECTURAL CONCLUSION: WHAT PATH IS AVAILABLE TO QATAR?
Qatar is the only country that simultaneously:
- Manages a $500 billion sovereign wealth fund aimed at economic tokenization [3][4].
- Is building a CBDC — the digital riyal — as infrastructure for large-scale payments [5][6][7].
- Legalizes tokenization of real estate, sukuk, equities, and ETFs [5][6][7].
- Prohibits cryptocurrencies through QCB Circular 6/2018 and QFCRA Alert 2019 [5][8][9].
- Invests in blockchain technologies through QIA’s $3 billion venture-capital program [3][4].
- Lost 96% of its LNG exports in a single quarter following the closure of the Strait of Hormuz [1][2].
Qatar Compared With Other Models
Unlike the UAE
Qatar is not building a universal “crypto hub.”
It is building institutional tokenization under full state control [5][6][7].
Unlike China
Qatar does not completely prohibit crypto.
Instead, it is creating parallel infrastructure without the same ideological pressure [5][6][7].
Unlike Saudi Arabia
Qatar is not participating in mBridge.
It is developing its own CBDC infrastructure [5][6][7].
Unlike Russia
Qatar has a strategy but has lost access to part of its resource monetization.
Russia has the resource but lacks a comparable strategy.
QATAR’S WEAK POINTS
1. Energy Blockade
96% of LNG exports lost in a single quarter.
There are no alternative routes [1][2].
2. Budget Deficit
$5.8 billion in one quarter — the largest since 2016 [1][2].
3. Cryptocurrency Ban
Bitcoin could potentially serve as an additional channel for monetizing energy, but it is prohibited [5][8][9].
4. Tokenization Without an Energy Derivative
CBDC and asset tokenization do not solve the problem of energy monetization [5][6][7].
5. Dependence on the Strait of Hormuz
Any major regional conflict creates a direct economic shock [1][2].
THE MAIN CONCLUSION
Qatar will not “import Bitcoin” like Europe.
It already has its own energy.
It will not necessarily “mine Bitcoin” like Russia or Iran.
Instead, it risks losing energy — megawatts that could potentially become part of global liquidity [1][2].
For Qatar, Bitcoin is neither an “energy coupon” nor simply an “instrument of survival.”
It represents an opportunity cost — a resource that the state currently prevents itself from using through its cryptocurrency restrictions [5][8][9].
CONCLUSION: HOW QATAR FITS INTO THE GLOBAL TRANSITION
Qatar is neither the architect of the new system nor simply its victim.
Qatar is a laboratory of strategic error.
Europe
Europe may remain a structural importer of Bitcoin because it lacks sufficient domestic energy resources.
China
China is building parallel infrastructure because it has a distinct strategic approach.
United States
The United States is attempting to preserve financial influence through Bitcoin reserves as the role of the dollar evolves.
Russia
Russia could potentially become more energy-sovereign if it develops an effective strategy.
Qatar
Qatar is building a tokenized economy through QIA, CBDC infrastructure, and institutional partnerships.
It is not making loud declarations about becoming a “crypto hub.”
It is simply building a parallel architecture.
But that architecture does not include an energy derivative.
Blockchain without Bitcoin is infrastructure without fuel.
GLOBAL SIGNIFICANCE
Qatar demonstrates how even a country with a deliberate strategy can face structural problems if it ignores the relationship between energy and digital assets.
The question is not whether Qatar will use Bitcoin.
The question is whether it can move beyond a paradigm of control — or remain trapped within its own strategy while its energy remains locked inside the Persian Gulf.
FULL LIST OF SOURCES
[1] Reuters — Qatar’s LNG exports plunge after Strait of Hormuz closure — March 2026
[2] Bloomberg — QatarEnergy halts Ras Laffan operations for first time in 30 years — March 2026
[3] MENA Fintech Association — QIA expands venture capital program to $3 billion — May 2026
[4] Gulf Times — QIA CEO: We explore blockchain, not crypto — April 2026
[5] Chambers and Partners — Qatar Digital Assets & Blockchain Infrastructure: Sovereign Compute & Regulation — March 2026
[6] QCB — Digital Rial Project: Foundation Stage Complete — September 2026
[7] QFC — Digital Assets Framework: Tokenization of Real Assets — September 2024
[8] QCB — Circular 6/2018: Prohibition of Cryptocurrency Trading — 2018
[9] QFCRA — Alert 2019: Virtual Asset Services Prohibited in QFC — 2019
© 2026, Editorial offices of Kafedra and SforNews.
Source attribution is required when quoting or reproducing this material.
🔗 MORE ANALYSIS — SforNews

Bitcoin
$62,881.23

Ethereum
$1,672.04

Litecoin
$42.71

Dash
$37.08

Bitcoin Cash
$209.43